Customer rewards
Understand the separate points, referral, review, and credit views in customer accounts.
Store credit is a balance belonging to a customer in your store’s currency. The customer signs in and chooses to apply it at checkout. It is not applied simply because they have a balance, and it is not a discount code.
Use manual credit for a documented goodwill adjustment. Review and referral rewards can also create promotional credit. The source matters: returning an order paid with promotional credit does not turn that promotion into ordinary, non-expiring money.
Go to Customers, open the customer, and select the Store Credit tab. The profile header also shows the personal balance.
Choose Issue Credit to open Issue Store Credit.
Enter a positive Amount in your store currency and an optional Note explaining the adjustment, then confirm.
Check the new ledger entry and balance before telling the customer it is available.
The current customer dialog has Amount and Note, with no expiry selector or remove-credit control. Credit issued from this dialog is non-expiring and is recorded as an adjustment. Expiring rewards use the terms of their issuing program; the presence of expiry support in the underlying credit system does not add an expiry field to this dialog.
Company-location credit is separate. The personal balance on a customer profile is not the company’s purchasing balance.
Credit is tracked in separate grants, each with its own origin, remaining amount, and possible expiry. An account may contain both expiring promotional credit and non-expiring manual credit.
| Term | What it means |
|---|---|
| Available balance | Credit currently available to spend, after reservations and expiry |
| Reserved | Credit temporarily held for a checkout being prepared; it is not available to another checkout |
| Issued / redeemed / expired totals | Historical activity, not three interchangeable spendable balances |
| Next expiry | The next relevant credit expiry, where supplied by the account view |
| Promotional adjustment | A record of a reward that was invalidated; it is not a cash bill |
Eligible expiring grants are used before non-expiring grants. Date-based credit expiry follows the store’s local day. A checkout reservation created before expiry can protect the amount it reserved for that reservation’s short lifetime; it does not extend the entire grant or keep an abandoned checkout alive forever. An imported exact expiry uses its saved instant. Expiry follows that promised boundary even if a scheduled expiry check runs later.
The customer’s Rewards page includes a searchable store-credit ledger with credit/debit filters, reasons, dates, and references. Reasons can include adjustment, order payment, refund, review reward, and referral reward. The admin customer page shows ledger history and a Load more control. Use these records to explain an adjustment rather than inferring spendable value from the original reward amount alone.
The referral view’s Lifetime net rewards is issued referral value minus actual recovery, not this available balance. Spending or expiry can leave the wallet empty while that historical figure stays positive. See the referral example for the effect of invalidation, recovery and waiver.
The customer signs in to the account that owns the balance.
They shop in Personal context. A company checkout uses the separate B2B credit rules; membership of a company does not convert personal rewards into company funds.
At checkout, they choose Apply for store credit and review the resulting amount due. They can remove it before completing the purchase.
The order records the actual credit consumed. Any remaining payable amount goes to the selected payment method.
Example: a ₹1,000 order uses ₹200 of credit and ₹800 paid through a gateway. The order records those two tenders separately. A displayed account balance is not permission to charge more credit than the customer applied.
The supported D2C refund flow restores credit that was actually used on the order. It does not offer a general “refund the customer’s card payment as store credit” conversion. The credit part is capped by the order’s remaining refundable credit payment. Promotional credit retains its original source and expiry; ordinary non-promotional credit follows a different renewal rule.
For the ₹1,000 order above, a full eligible refund has a ₹800 gateway component and a ₹200 original-credit component. If the credit is still valid, its credit component can return to the account. If promotional credit has expired, the refund does not create a fresh expiry period. For a source without promotional ancestry, the current restoration flow removes an already-passed expiry and restores it as non-expiring credit. Check the refund result for the amount actually restored and any amount withheld; do not apply the ordinary-credit renewal rule to rewards.
See refunds and returns for refund preview, payment processing, and the order’s remaining refundable amounts.
A purchase-based referral reward can stop qualifying when a cancellation, return, or refund makes its qualifying purchase ineligible. An honest review incentive is different: an ordinary return or low rating does not invalidate it. Review reward reversals concern reasons such as confirmed fraud, deletion, or removal of required review content; see collecting reviews. When a promotional source is invalidated, its recovery position records:
| Field | Meaning |
|---|---|
| Reversed | The promotional amount invalidated |
| Recovered | Value removed or withheld through recovery |
| Waived | Outstanding promotional value the merchant has chosen to absorb |
| Expired before reversal | Value already unavailable because it expired |
| Outstanding | Promotional benefit not yet recovered, expired, or waived |
Expiry example: ₹100 promotional credit expired yesterday but has not yet been processed by the scheduled expiry check. If its qualifying purchase is invalidated today, that unused ₹100 is classified as expired, not recovered. If ₹60 had already been spent and only ₹40 remained at expiry, ₹40 expires and ₹60 can remain outstanding. The result does not depend on which background check runs first.
Unspent invalid promotional credit is removed from availability. If the customer already spent it, the remaining exposure is recorded against that promotional source. It does not authorize taking an unrelated cash refund or charging the customer’s payment method. A later refund of the purchase that spent that same credit is a recovery opportunity. If a checkout already reserved some of the source, invalidation can wait for that checkout to settle or release its reservation.
Diagram viewer: scroll horizontally to inspect the full flow.
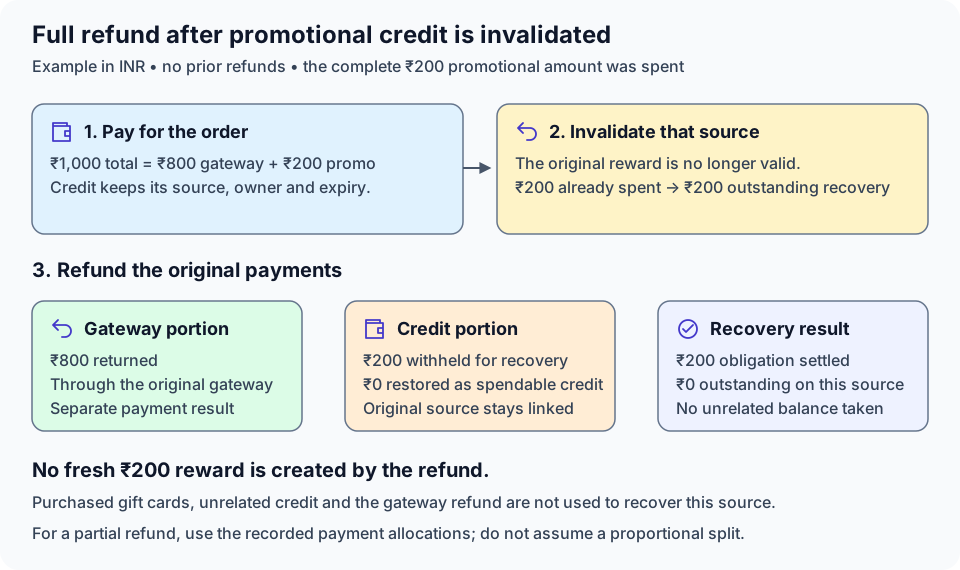
Assume a ₹200 promotional grant was fully spent on the ₹1,000 order and then invalidated because its qualifying purchase was refunded. No part of the grant had expired or been waived.
| Step | Gateway refund | Spendable credit restored | Recovery outstanding |
|---|---|---|---|
| Promotion invalidated after being spent | No refund on this order yet | ₹0 | ₹200 |
| Full refund of this order | ₹800 | ₹0; ₹200 original credit is withheld | ₹0 |
The ₹200 is recovered once through withholding its return to the balance; it is not also subtracted from the ₹800 gateway refund. For a partial refund whose preview allocates ₹400 to the gateway and ₹100 to this original credit, the corresponding result is ₹400 externally, ₹0 credit restored, and ₹100 recovery still outstanding. Allocation depends on the refund preview and original tender, not on a new reward rate.
In Loyalty, open the member’s details and find Promotional reward adjustments. An outstanding adjustment offers Waive outstanding amount and requires a reason. A waiver means the merchant accepts that promotional cost.
A waiver does not itself issue credit, refund cash, or extend an expiry. If the original, unexpired credit later returns through a refund, a waiver can permit that value to become available instead of being withheld. For example, waive ₹200 before refunding the example order: the original ₹200 may then be restored, while the ₹800 external refund is unchanged. If the original credit has expired, the waiver does not revive it.
Customer rewards
Understand the separate points, referral, review, and credit views in customer accounts.
Refund workflow
Review the original payment split in refunds and returns.
Settings and recovery
Follow Rewards: settings and recovery when an accepted offer, expiry or repeated request needs explanation.
Gift cards
Compare account credit with purchased bearer cards and legacy personal reward cards in gift cards.